Learn & grow

Learn money. Keep more of it.

Notch is built to teach. Every screen explains what your numbers mean and what to do next, because understanding your money is the surest way to keep more of it.

Our mission

Most of us were never taught this. We think your money app should teach you.

Financial literacy isn't about being good at math. It's knowing what questions to ask, and having someone explain the answers in plain English. That's what Notch is for.

49%of personal finance questions answered correctly by U.S. adults, on average, unchanged since 2017
38%for Gen Z, the lowest of any generation
36%on questions about risk, the hardest area for Americans

Source: 2025 TIAA Institute–GFLEC Personal Finance Index, a national survey with Stanford's Global Financial Literacy Excellence Center.

How it works

Understand. Decide. Save.

Notch turns learning into a habit you build every time you open the app.

1

Understand your numbers

Every number has a ? that explains it in plain English: P/E, escrow, cap rate, utilization. No jargon left unexplained.

2

See your options

Lessons, calculators and Ask Notch use your real accounts, so you see what a choice means for you, not a made-up example.

3

Keep more of what you earn

Small, steady wins: a canceled subscription, a paid-off card, an extra mortgage payment. Every notch is a win.

Learning that saves

What you learn, what it can save.

Real examples of how understanding one idea turns into real money.

Forgotten subscriptions

You learn: small monthly charges add up fast.

Notch shows: every subscription, with its yearly total.

$576a year: three $15.99 subscriptions

Credit card interest

You learn: which debt to pay first (avalanche vs. snowball).

Notch shows: each card's balance and rate.

$1,200a year in interest on $5,000 at 24% APR

Investment fees

You learn: what an expense ratio is, and why it matters.

Notch shows: your holdings and their key numbers.

$950a year: 1% vs. 0.05% fees on $100,000

Paying extra on a mortgage

You learn: how extra principal shortens a loan.

Notch shows: a pay-extra slider with your real loan.

$103,000less interest: $200/mo extra on $300,000 at 6.5%, paid off ~7 years sooner

An emergency cushion

You learn: how big a cushion should be, and where to keep it.

Notch shows: a goal linked to your savings account.

No new debtwhen the car breaks down, because the money's already there

Spending pace

You learn: fixed vs. flexible costs.

Notch shows: where you'd expect to be today, mid-month.

Mid-monthis when you can still change course, not after the bill arrives

Examples are illustrative; your results depend on your own numbers and choices. Notch is education, not financial advice.

Learning path

From the basics to building wealth.

Five levels, in the order most people need them. Start anywhere.

Level 1

Foundations

Know where your money goes, and build a cushion.

In the app: Budget, Cash flow, Recurring
Level 2

Debt & credit

Pay less interest, and protect your score.

In the app: Accounts, Loan calculator
Level 3

Investing

Grow what you save, without the jargon.

In the app: Portfolio, Market watch, Growth calculator
Level 4

Homes & real estate

Own a home, or a rental, with your eyes open.

In the app: Real Estate, Afford-a-home calculator
Level 5

Planning together

Line up your money, your partner and your future.

In the app: Plan, Household, Ask Notch
Inside the app

Lessons that use your numbers.

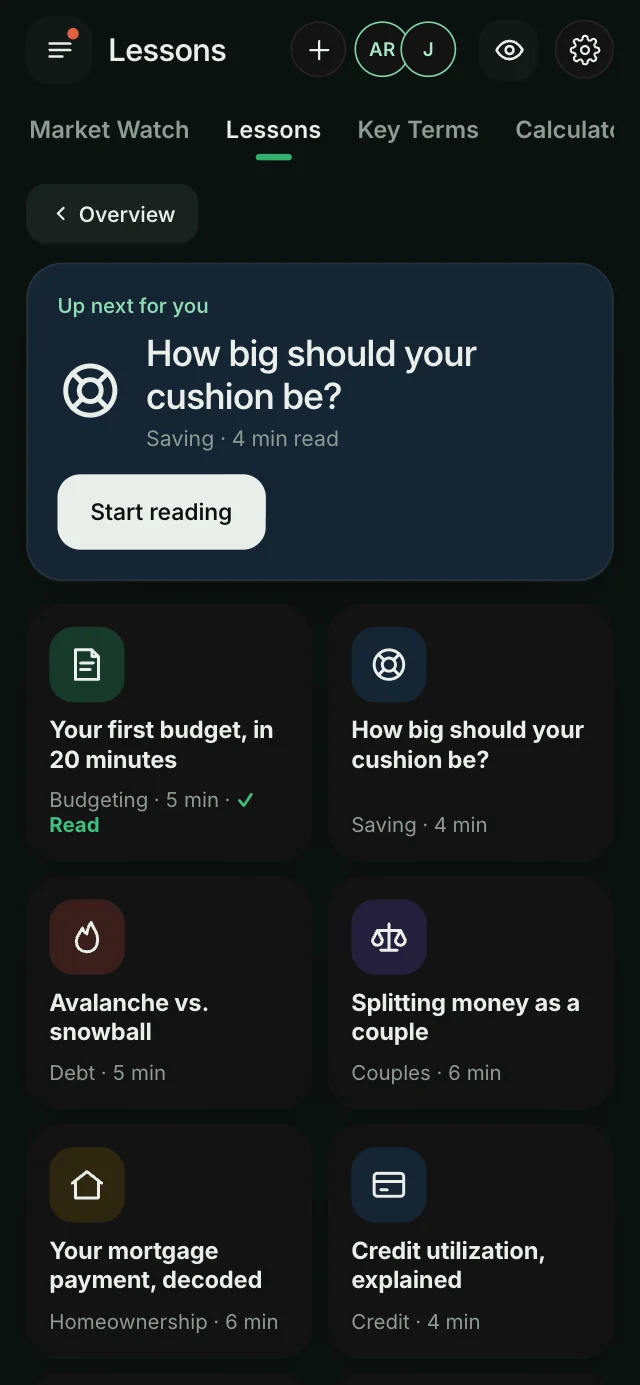
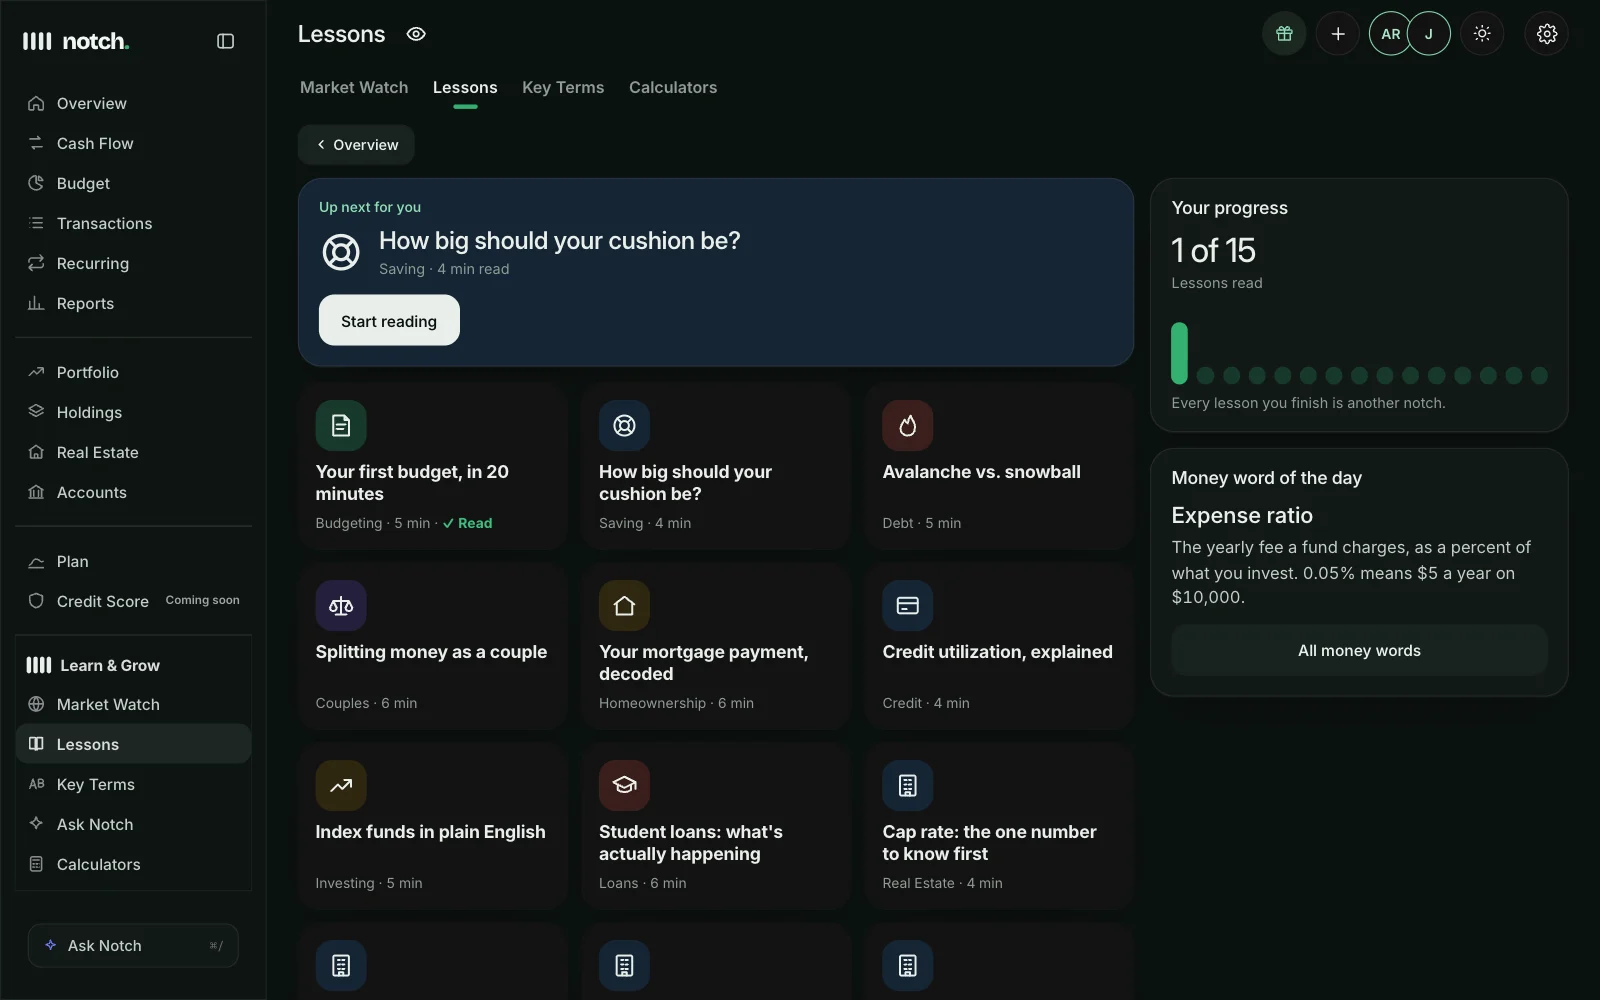
Short lessons with progress, a money word of the day, and a key-terms library from APR to cap rate. Each one links to the calculator or page where you can try it.

  • Lessons you can finish in a few minutes
  • Every money word, explained
  • Try it in a calculator, with your numbers
notchmoney.io
Lessons on the web
Lessons on iPhone
Ask anything

No question is too basic.

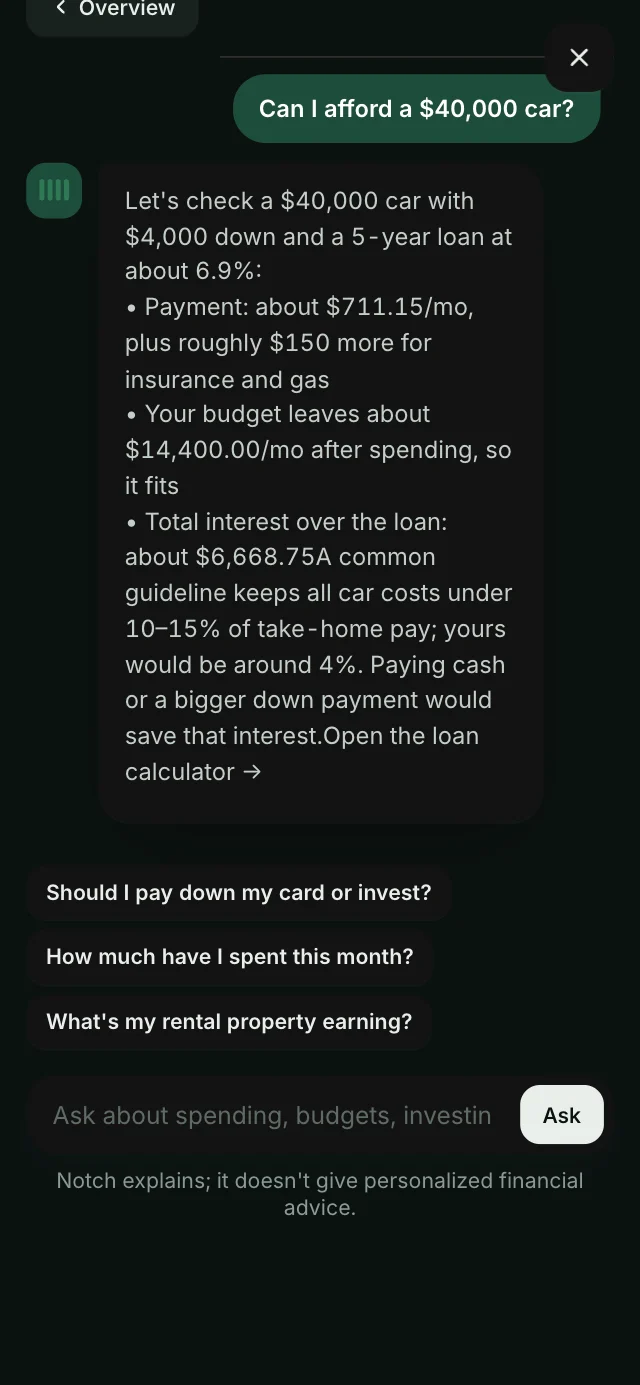
Ask Notch what an index fund is, whether you can afford a car, or what your rental really earns. It answers with your numbers, and never makes you feel behind.

  • Plain-English answers
  • Built from your accounts and plans
  • Education, not a sales pitch
Ask Notch
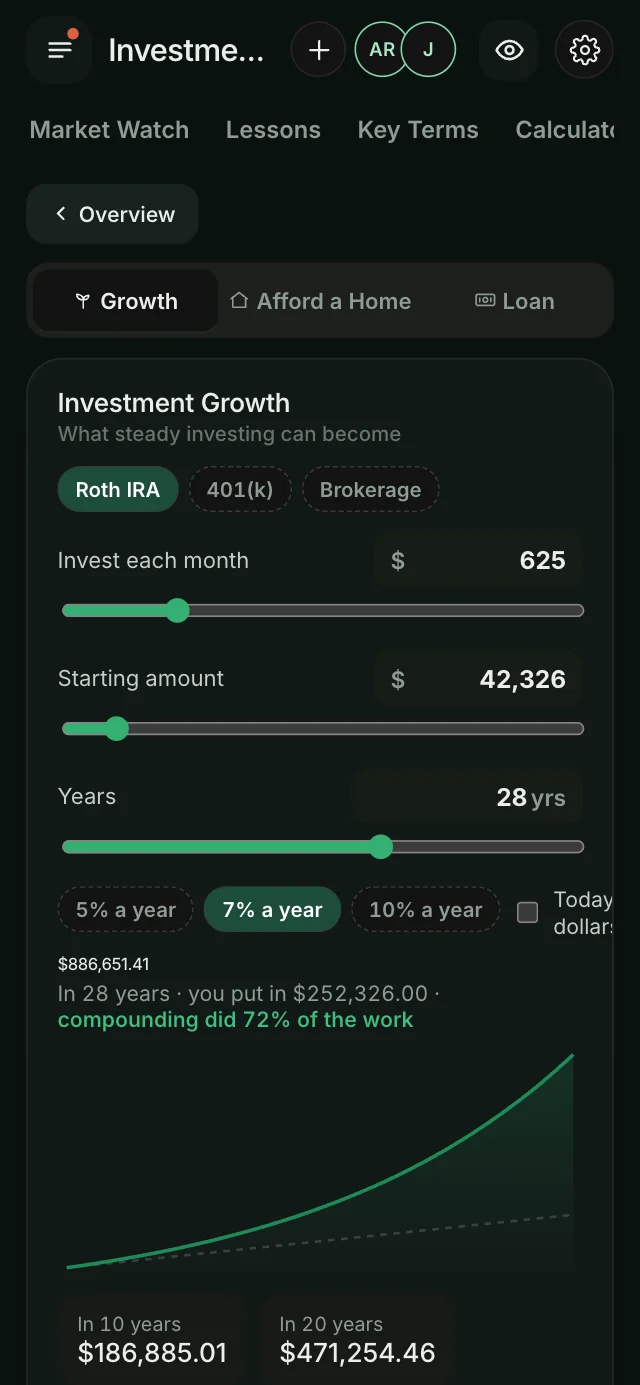
Calculators
Markets, explained

The news, translated.

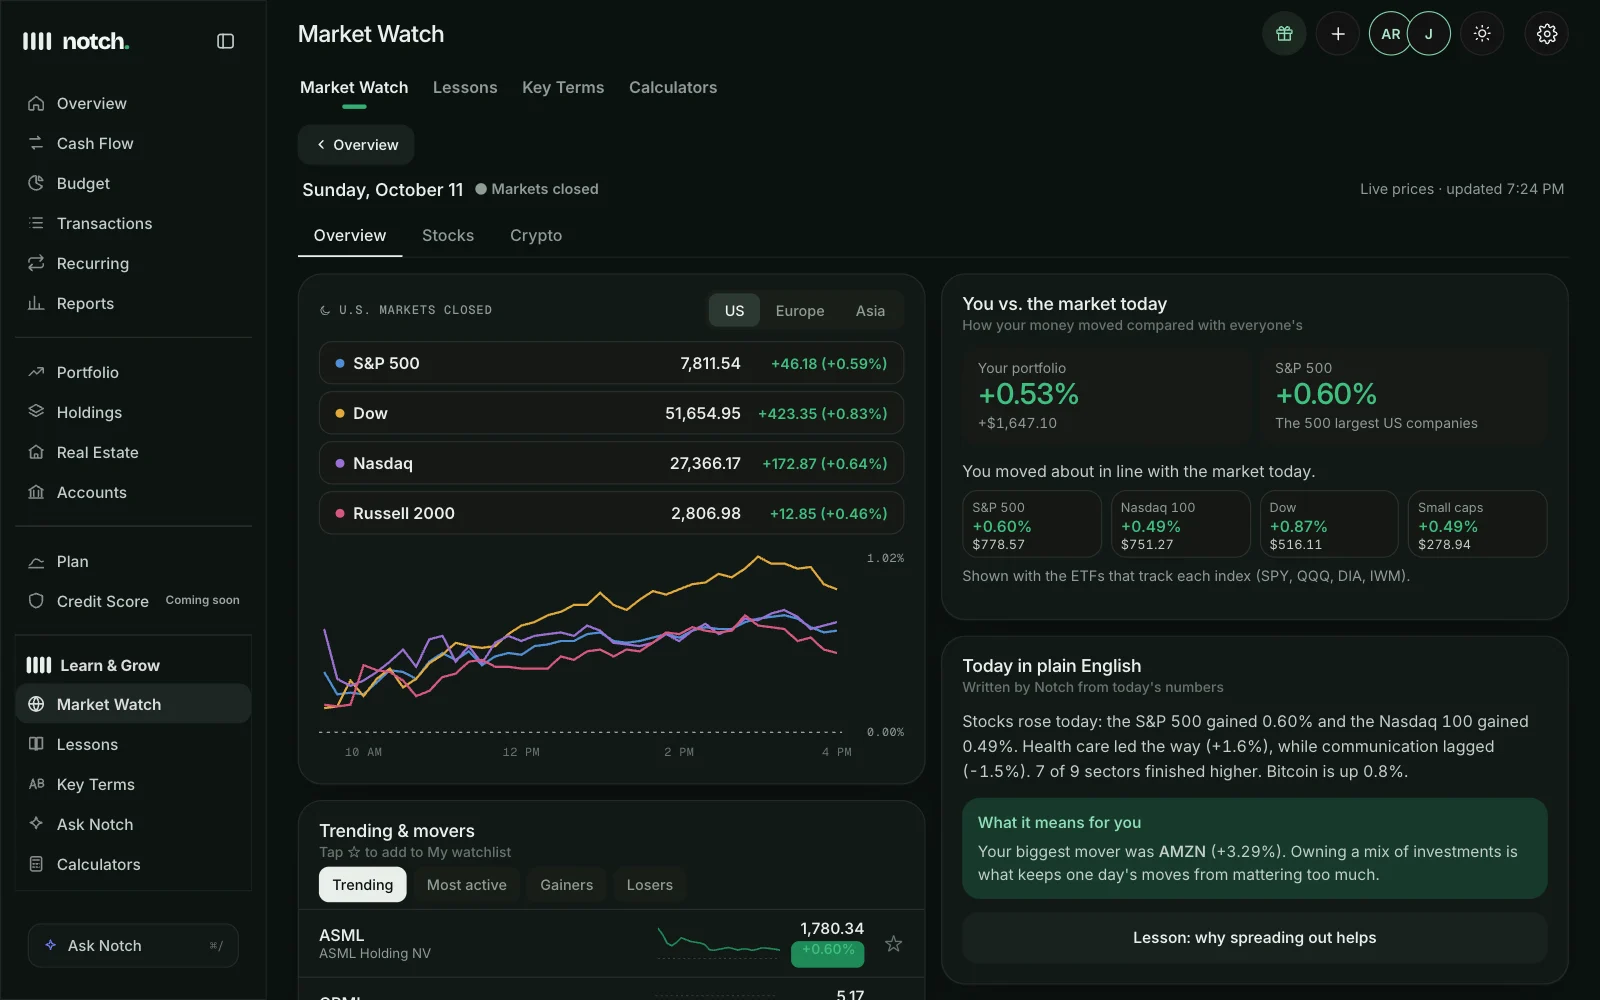
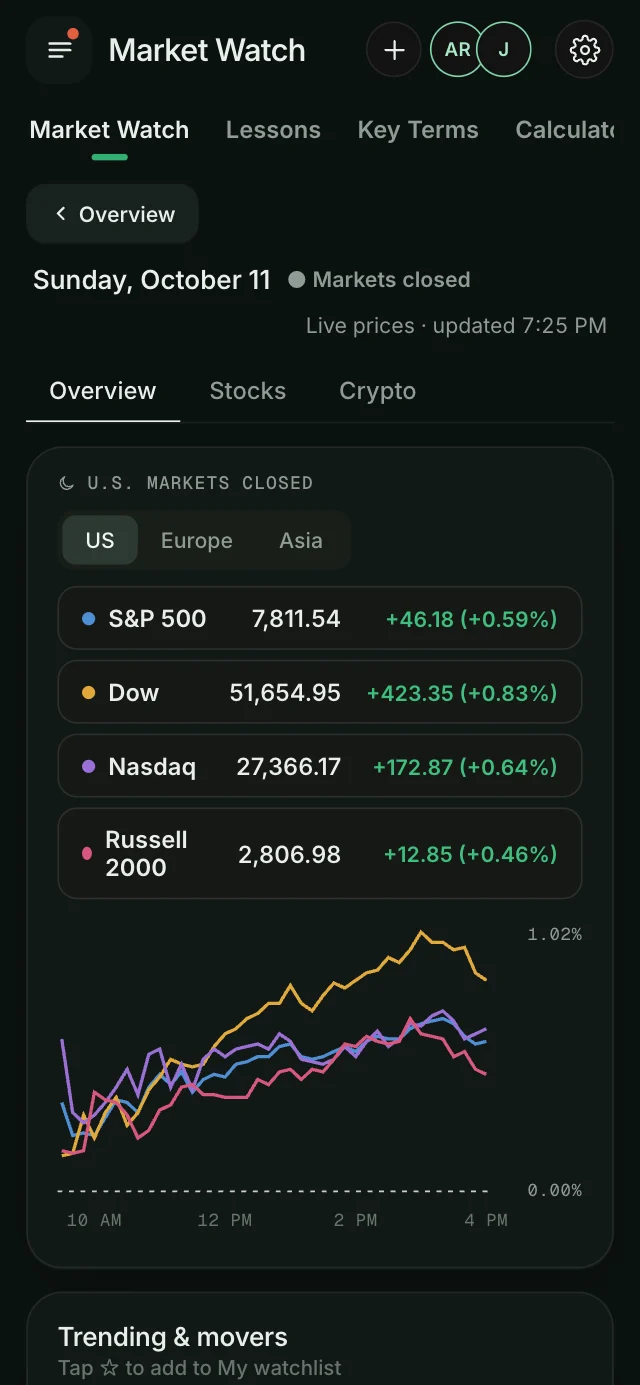
Market watch explains what moved today and what it means for what you own, with a calm long view for rough days.

  • You vs. the market, every day
  • Today in plain English
  • Every big drop, in context
notchmoney.io
Market watch on the web
Market watch on iPhone
Money guides

Pick a topic. Learn it in minutes.

Free for everyone, whether or not you use Notch.

Notch guides are general education, not financial, tax or investment advice. For decisions about your situation, consider a licensed professional.

The Notch Basics

Six habits, zero spreadsheets.

Simple principles that hold up whatever your income, whatever your goals.

1

Know where it goes

You can't steer what you can't see. Get every account in one place and look at real numbers, not guesses.

2

Build a cushion first

A few months of essentials set aside turns emergencies into inconveniences.

3

Knock out expensive debt

High-interest debt is a guaranteed loss. Paying it off is a guaranteed win.

4

Plan for what's coming

Bills, birthdays and car repairs aren't surprises. Give them a line before they show up.

5

Let time do the lifting

Money you won't need for years can grow. Start small, stay steady, ignore the noise.

6

Talk about it

Money goes smoother when it's a team sport. Check in monthly, and celebrate wins together.

Our promise

Education, never a sales pitch.

We will

  • Explain things in plain English
  • Use your real numbers, not made-up examples
  • Show the trade-offs, not just one answer
  • Keep lessons and guides free to read

We won't

  • Push credit cards, loans or products
  • Earn commissions on what you choose
  • Make you feel behind
  • Pretend to be your financial advisor

Learn it. Use it. Keep more.

Seven days of Notch Pro free, your partner too.

Budgeting

Your first budget, in 20 minutes

A budget isn't a diet. It's a plan for money you already have, so it goes where you want instead of wherever it drifts.

1. Look back before you plan ahead

Pull up the last three months of spending. Notch does this for you in Cash flow and Reports. Averages beat guesses: most people underestimate dining and shopping by a lot.

2. Split fixed from flexible

Fixed costs barely change: rent or mortgage, insurance, loan payments, phone. Flexible ones move: groceries, dining, shopping, fun. Fixed costs are mostly decided already; flexible is where your choices live.

3. Set limits on the flexible stuff

Start with your three-month average, then trim one or two categories by 10–15%. Small, believable cuts stick. Dramatic ones get abandoned by week two.

4. Leave a buffer

Something always comes up: a birthday, a car repair, a co-pay. A "miscellaneous" line of a few percent keeps one surprise from blowing up the whole plan.

5. Check in, don't check out

Glance at your pace once a week and adjust at the end of the month. Going over isn't failure; it's information about what the real number is.

Try Notch free
Saving

How big should your cushion be?

An emergency fund is money set aside for the things you can't schedule: a job gap, a medical bill, a blown transmission. It's what keeps a bad week from becoming credit card debt.

The common rule of thumb

Many planners suggest 3 to 6 months of essential expenses: housing, utilities, groceries, insurance, minimum debt payments and transportation. Not your total spending, just what you'd need to keep the lights on.

When to aim higher

Consider leaning toward six months or more if you're self-employed or on commission, if your household relies on one income, if you own a home (roofs and boilers don't warn you), or if your industry is prone to layoffs.

Where to keep it

Somewhere boring and reachable. High-yield savings accounts at FDIC-insured banks are a popular choice: they pay more than a typical savings account and your money stays available. This isn't money to invest in the stock market, since it needs to be there when you need it.

How to build it without noticing

Start with a first milestone, like $1,000, then automate a transfer on payday. In Notch, create a goal and link the savings account so progress updates itself.

Try Notch free
Debt

Avalanche vs. snowball

Two popular ways to pay off multiple debts. Both start the same way: pay the minimum on everything, then send every extra dollar to one debt at a time.

The avalanche: highest interest rate first

Put extra money toward the debt with the highest APR. When it's gone, roll that payment into the next-highest. Mathematically this saves the most interest, often a lot when credit cards charge 20% or more.

The snowball: smallest balance first

Put extra money toward the smallest balance, regardless of rate. You knock out whole debts sooner, and those quick wins keep many people motivated enough to finish.

So which wins?

The avalanche wins on paper. The snowball wins for people who'd otherwise quit. The best plan is the one you'll stick with, and a hybrid works too: clear one tiny balance for momentum, then switch to highest rate.

A quick way to see the stakes

A $5,000 card balance at 24% APR costs roughly $1,200 a year in interest. Every extra dollar you put toward it earns you a guaranteed "return" equal to that rate. Notch's debt payoff plan shows your debt-free date and how much each extra payment saves.

Try Notch free
Couples

Splitting money as a couple

There's no right way to share money, only the way that feels fair to both of you. Here are the three most common setups.

1. Split everything 50/50

Simple and easy to track. It works well when you earn similar amounts. When incomes differ a lot, the lower earner can end up stretched on shared costs while the higher earner has plenty left over.

2. Split by income

Each person pays the same percentage of their income toward shared costs. If one of you earns 60% of the household income, they cover 60% of rent and groceries. Many couples find this feels fairer when paychecks are uneven.

3. One shared pot

Both paychecks go into a joint account that pays for everything, and each person gets an equal amount of personal "no questions asked" money. This works well for couples who think of money as fully shared.

Make it a conversation, not a spreadsheet

Pick a setup, try it for a couple of months, and revisit it when life changes: a new job, a move, a baby. In Notch you can choose 50/50, by income or custom percentages, set exceptions by category, and let Even up keep a running tally of who's covered more.

Try Notch free
Homeownership

Your mortgage payment, decoded

A monthly mortgage payment usually has up to four parts, often called PITI.

Principal and interest

Principal pays down what you borrowed. Interest is the cost of borrowing. Your combined principal and interest payment stays the same on a fixed-rate loan, but the mix changes every month.

Why early payments feel like they barely move the balance

Interest is charged on what you still owe, so early on most of each payment goes to interest. On a 30-year loan at around 6.75%, the first payments are well over 80% interest. Over time the balance shrinks and more of each payment goes to principal. This schedule is called amortization.

Escrow: taxes and insurance

Many lenders collect property taxes and homeowners insurance with your payment and hold it in an escrow account, then pay those bills for you. Escrow can change each year when taxes or premiums change, even though your principal and interest don't.

Extra principal

Any extra you pay toward principal reduces the balance right away, which cuts future interest and can shorten the loan. Many lenders let you mark extra payments as "principal only."

At tax time

Your lender sends Form 1098 showing the mortgage interest you paid, including interest prepaid at closing. Notch tracks this month by month so you're never surprised.

Try Notch free
Credit

Credit utilization, explained

Credit utilization is how much of your available credit you're using. If you have a $10,000 limit and a $2,500 balance, your utilization is 25%.

Why it matters

It's one of the biggest factors in credit scores. Lower usage generally signals that you aren't stretched thin.

The commonly cited marks

Keeping overall utilization under 30% is widely recommended, and people with the highest scores often stay under 10%. Both your total across all cards and each individual card can matter.

The timing trick most people miss

Card issuers usually report the balance on your statement, not on your due date. So even if you pay in full every month, a big balance on the statement date can show high utilization. Paying some of it down before the statement closes keeps the reported number low.

What not to do

Closing an old card lowers your total available credit, which can raise your utilization. If a card has no annual fee, keeping it open is often the better move.

Notch shows each card's utilization with the 10% and 30% marks, so you can see where you stand at a glance.

Try Notch free
Investing

Index funds in plain English

An index fund is a single investment that holds every company in a market index, like the 500 large U.S. companies in the S&P 500. Buy one share, and you own a sliver of all of them.

Why people like them

Diversification: one company having a bad year barely dents a fund holding hundreds. Low cost: because they simply follow an index, many charge very low yearly fees, called expense ratios. Over decades, small fee differences add up to real money.

What to know before you buy

Index funds go up and down with the market, sometimes sharply. They're generally a tool for money you won't need for five or more years, so you have time to ride out the dips. Money for an emergency fund or a near-term purchase usually belongs somewhere steadier.

Where people hold them

Common places include workplace retirement plans like a 401(k) (especially if your employer matches contributions), IRAs, and regular brokerage accounts. Each has different tax rules and limits.

This is general education, not investment advice. Consider talking with a licensed professional about your situation.

Try Notch free
Loans

Student loans: what's actually happening

Student loans can feel like a black box. A few basics make them much easier to manage.

Interest builds every day

Federal student loans use simple daily interest: each day, interest accrues on your principal balance. When a payment arrives, it typically covers any fees and accrued interest first, and the rest reduces principal.

You probably have several loans, not one

Each school year usually created separate loans with their own rates, such as Direct Subsidized and Direct Unsubsidized. Your servicer shows them together, but each has its own balance and rate. Notch lets you enter each one.

Repayment plans

Federal plans have included Standard (fixed payments, usually over 10 years), Graduated (payments start lower and rise), Extended (longer term, lower payments, more interest), and income-driven plans that tie payments to what you earn. Which plans are available has changed in recent years, so check StudentAid.gov for what's open to you today.

Paying extra

Extra payments usually go toward interest first, then principal. If you want to target your highest-rate loan, ask your servicer how to direct extra payments.

This is general education. Your servicer and StudentAid.gov have the details for your loans.

Try Notch free

You're early!

Notch is opening in waves. Leave your email and we'll send your invite, with your free trial ready to go.

Have an invite already? Create your account